Frost Valley Ads: Where Merging Meets Meaningful Stories
Frost Valley: Merge & Story ran 1,296 creatives and 2,218 ad plans across October on a three-source channel book — AdMob, Meta and AppLovin at comparable weight — anchored by a 383-plan India exclusive.
Emma Lee
Editorial Research Contributor
Published
Updated
Frost Valley Ads: Where Merging Meets Meaningful Stories
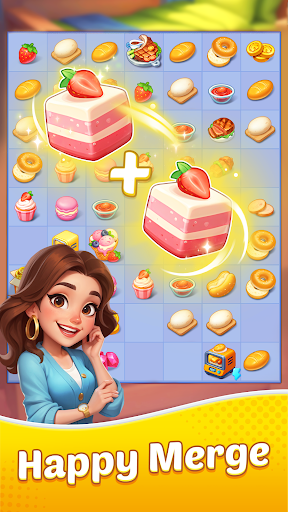
"Bring Frost Valley to life — Where merging meets meaningful stories!" runs one of the title's own creatives, and the delivery behind it is just as layered: 1,296 creatives and 2,218 plans across October, a three-source channel book at comparable weight, and an India core that carries the deepest exclusive block in the set.
What this breakdown covers
- Scale first. Across October the record ran 1,296 creatives and 2,218 ad plans, with 181 creatives carrying a reinvestment flag and 429 million in estimated lifecycle exposure across the active set. The store label reads above 10 million downloads.
- Two mid-window jumps. October 28 lifted creatives to 582 (a 204-unit supply day); October 28 moved both axes together — 204 new creatives and a plan climb to 1,014 at month end. Both lines finished above where they started.
- Three sources at comparable weight. AdMob 44.9 percent, Facebook and Audience Network 27.5 percent each, AppLovin 26.3 percent — a three-source supply structure instead of the usual dominant-rail-plus-second-line.
- An India anchor. India 44.3 percent of plans with 383 targeting India alone — the deepest block by far; Brazil holds 44 exclusives. A broad shallow tier follows.
- Long-lived AppLovin units. A video and two playables opened in April and May were still active in November at 4.6–6.6 million estimated exposure each — a seven-month shelf.
- Four supply batches across the month. October 13, 20, 28 and 31 — the biggest a 204-creative drop on October 28 that coincided with the plan climb to 974.
The shape of October: a dip, then a climb
Frost Valley: Merge & Story is a merge-and-decoration title from LITEORANGE CREATION, and its October book runs as a dip and a climb. The base is stable and large: between 690 and 925 plans in delivery every day, with creatives in the 320–470 band. October 9 is the dip — plans fell to 694 as the book trimmed. October 28 is the inflection — 204 new units in a day, lifting the creative count from 406 to 582 while plans jumped to 974, and the month closed at 1,014 plans on 602 creatives.
Both axes moved in the same direction at month end: the supply jump and the plan climb arrived together on October 28, unlike the supply-first-then-delivery sequencing this site documented on Smash Away!'s second ignition. Here the October 28 restock and the plan climb were one move — supply and delivery committed in the same stroke.
An India anchor, and a wide shallow tier
The market map centers on two countries that rarely anchor casual books. India: 44.3 percent of plans, with 383 targeting India alone — the deepest exclusive block by far. Pakistan: 29.0 percent with 38 exclusives; Brazil holds 44. Together they account for a South Asian core that carries its own builds, its own bidding logic, and more than a quarter of the book's exclusive weight between them.
The second tier is broad and layered. Australia at 22.1 percent rides the fanned book with almost no exclusives; Germany and France at 17.9 and 17.8 percent likewise. The United Kingdom, Singapore, South Africa and Spain fill a band between 21 and 23 percent with almost no exclusive presence. Ten markets, and 190-plus observed overall — India is the only deep-commitment market in October.
The India core is also the reason the book's scale holds. Market-exclusive plans carry targeting logic that only makes sense in one market, and 383 of October's exclusive plans sit in India alone — more than all other markets combined. That is a level of local commitment most casual merge books never build, and it explains why a title with a 10-million-plus label keeps spending at this level: the second-tier markets are not leftovers, they are separate books with their own economics.
Three rails at comparable weight
The channel structure is the least conventional part of this book. AdMob leads at 34.5 percent (765 plans), but AppLovin sits at 32.1 percent with 711 plans of its own, and Facebook and Audience Network each cover 30.9 percent on the same 686-plan count. Three supply sources — Google, the Meta pair, and the largest independent network — at weights within eighteen points of each other.
The creative supply maps onto those rails cleanly. The AppLovin rail holds the long-lived layer: a video opened April 15 and two playables from April 23 and May 3, all still active in November, at 4.6–6.6 million estimated lifetime exposure each — a seven-month shelf. The Meta pair carries the fanned book across the month. Each source does a different job, and none is a token presence.
What to copy, and what to doubt
Three things here are portable. One: the three-source structure — AdMob, Meta pair, and AppLovin at comparable weight — diversifies supply risk in a way the two-rail books this site usually documents do not, and the creative layers map onto the rails by job rather than by accident. Two: the sequencing discipline of the two jumps — supply in October, delivery in November — keeps expensive creative decisions and cheap delivery decisions on separate calendars. Three: the India anchor shows a merge title can build 383 market-specific plans for a single market — more than all others combined — rather than treating it as a spill from a Western-first fan.
What to doubt is the quiet part. This teardown sees delivery, not outcomes: no retention, revenue or actual cost data appears here, and the download label is a public store snapshot. The three-rail structure may reflect network-side deals or measurement quirks as much as strategy. And the November plan climb ran while creatives were falling — which marks confidence in the October supply, but could equally be a buyer with no alternative. It can say where the book ran and how it moved. It cannot say what the buyer knew.
Track multi-rail books like this one dailyCreativeScope monitors creative intake, plan openings and market rotation across 40+ networks — so a supply jump shows up in your feed the day it happens.
FAQ
- What is Frost Valley: Merge & Story?
- A merge-and-decoration title from LITEORANGE CREATION PTE. LTD. with a public Google Play download label above 10 million (internal snapshot 14.66 million). This breakdown covers its ad delivery across October 2026.
- How big is the book?
- 1,296 creatives and 2,218 ad plans across October, with 181 creatives carrying a reinvestment flag and 429 million in estimated lifecycle exposure across the active set.
- Which markets lead?
- India at 44.3 percent of plans with 383 targeting India alone - the deepest exclusive block by far; Brazil holds 44 exclusives. Pakistan and a broad second tier follow. 190-plus markets observed.
- Why is the channel mix described as three rails?
- AdMob at 34.5 percent, the Facebook-Audience Network pair at 30.9 percent each, and AppLovin at 32.1 percent carry comparable weight — three supply sources at similar scale, unlike books that pair one dominant rail with a thin second line.
- What does the creative supply look like?
- A long-lived AppLovin layer — a video and two playables opened in April and May, still active in November at 4.6 to 6.6 million estimated exposure each — alongside Google-side sibling batches in mid-November, one with 144 clones and one with 43.
- What are the data caveats?
- Creative and plan counts are deduplicated delivery records per Asia/Shanghai natural day; channel and market coverage overlaps and does not sum to 100 percent; exposure figures are global lifecycle estimates; download figures are Google Play net snapshots. No install, retention or revenue data is used.
Figures are CreativeScope delivery estimates for the period stated; creative and plan counts are de-duplicated, daily counts are per natural day, and download figures cover Google Play only. Channel and market shares are based on plan coverage with multi-attribution, so they overlap and do not sum to 100%. No install, retention or revenue data is used.
Get this live in your agent
These rankings come from a single MCP tool. Free key, ask in plain English.
Full genre × market grid?
Team plan unlocks every genre and market cut, plus AI teardowns.